Unqualified buyers stall diligence
A buyer who cannot fund the purchase, or who does not know the business, still asks for the financials, the lease, and the customer list. Then the questions stop, and your file sits while you wait.
 Team Sign In / Sign Up
Florida Business Exchange
We already have 39,929 buyers in our database looking for a business just like yours.
See buyers that match your businessA sale starts with people who can buy. This is the FBX book of buyers, and the work already closed.
IBBA Platinum Chairman’s Circle
Axial Top 25 Lower-Middle Market Firm
BBF Top Producer
BBF Top Dealmaker
BBF Top 50 Business Broker
BBF Million Dollar Plus
IBBA Outstanding Producer
Before you take it to market
A buyer who cannot close still takes the business into diligence. That costs time, price, and privacy.
A buyer who cannot fund the purchase, or who does not know the business, still asks for the financials, the lease, and the customer list. Then the questions stop, and your file sits while you wait.
A buyer who is still arranging a loan is not ready to close. When the bank or the investor says no, the deal ends after the business has already been opened up.
Deep into diligence, a single buyer comes back and asks for a lower price. With no one else at the table, that concession is yours to make, or the sale stops.
Employees, customers, and competitors should not be the ones who learn the company is for sale. Every extra week, and every extra person pulled into a slow review, makes that more likely.
A sale that should move on a set timeline stretches across a season. You are still running the company, and you are also running a process that is not going anywhere.
Attention moves off customers and onto a deal that will not close. Revenue softens, staff get uneasy, and the numbers a buyer is underwriting get worse than the ones you started with.
How the sale is run
Who is at the table decides the price, the pace, and how much room you have to negotiate.
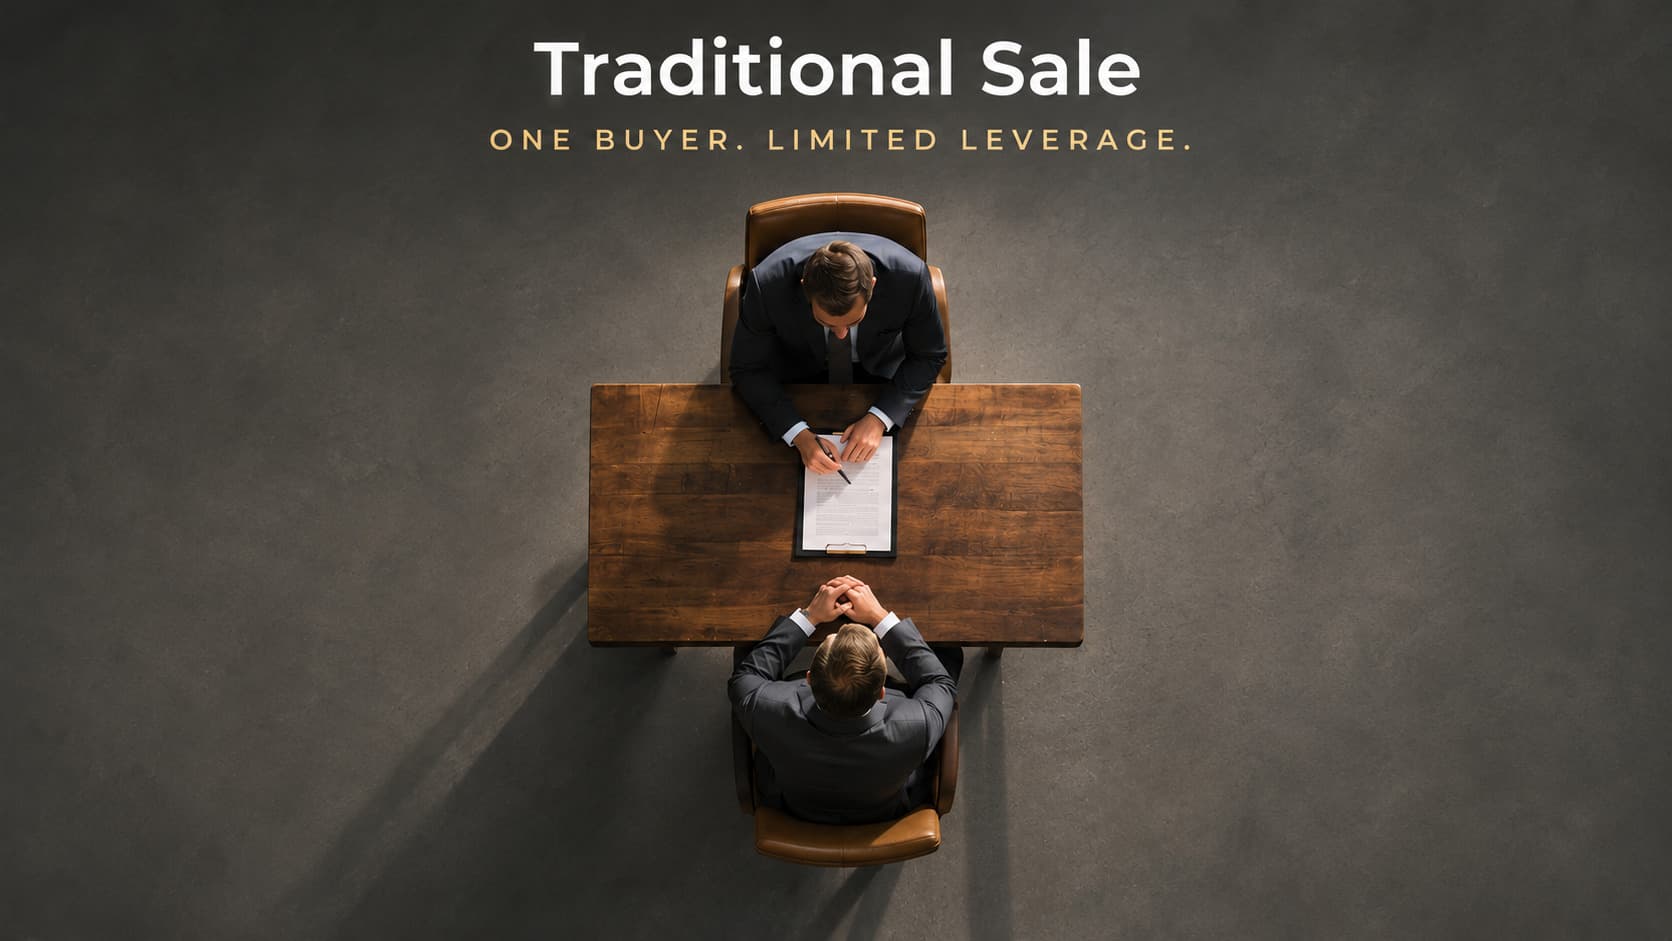
Traditional Sale
One buyer chooses the price, the structure, and the pace. You have no leverage. Push back, and the only path is to start over.
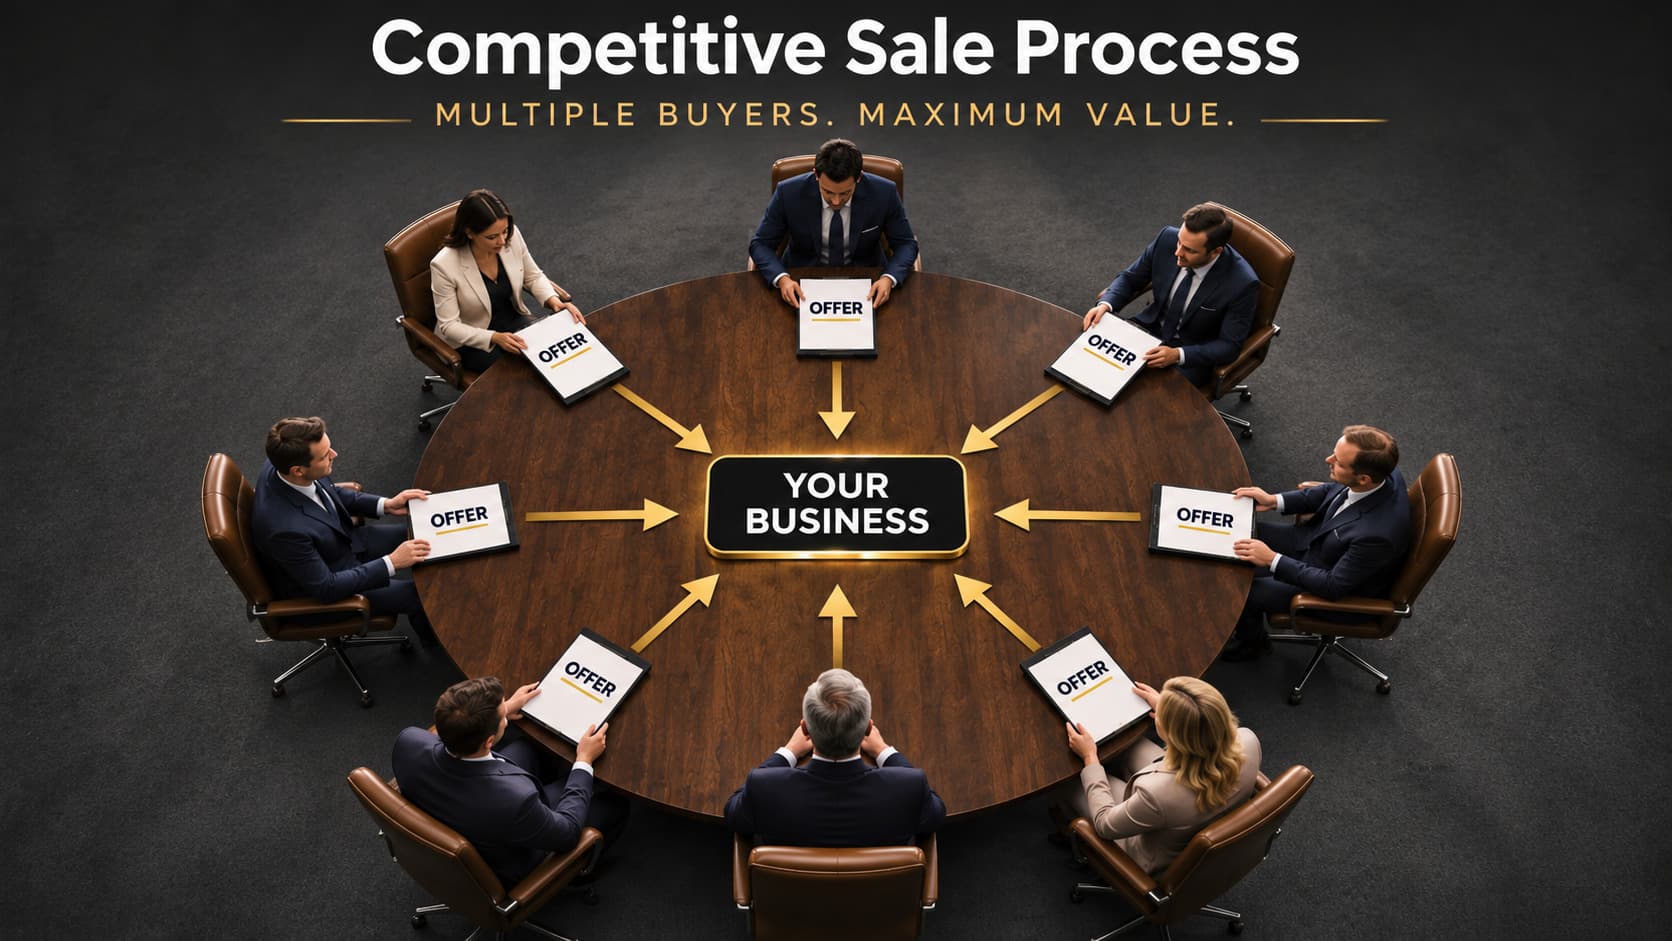
Competitive Sale Process
Several buyers who can close are in the process together. That competition supports a higher valuation, keeps momentum, and produces better terms.
Our process
The match count is the first look. The sale itself follows a private process with FBX.
We review the business in private and tell you what a buyer can pay.
The numbers, the story, and what stays confidential are set before anyone sees the business.
Your business is compared with buyers already in the database, including private equity groups.
Interest comes in together, so more than one buyer is talking about price and terms.
The buyer who fits stays on a timeline. The questions get answered once.
Price, structure, and the handoff are in writing.
Questions owners ask
Yes. The match page asks for industry, state, asking price, and earnings. You get a count of buyers who fit. No account is required.
This page does not publish your business. On the match page, buyer names and contact details stay hidden. You decide whether to talk with FBX before anyone is contacted.
A buyer who cannot fund the purchase stretches diligence, and often walks. Financing can fall through. The price can get cut late. The longer it runs, the more people who should not know have a chance to find out, and the business itself can slip.
One buyer sets the terms and the timeline. Several buyers who can close have to compete. That supports the valuation, keeps the file moving, and gives you better terms.
You can ask FBX to follow up on the buyers you select. A broker can walk through them with you and, if you want to sell, start with a confidential valuation.
Yes. The count of private equity groups on this page is the current number in the database. The match page then narrows the full buyer list to people who fit your business.
The buyers are already in the database. See how many match before you share the business any further.
See buyers that match your business